
3 Things Investors Might Not Know About Rivian's $4.5 Billion Loan
 2026-10-23 12:05
•Daniel Miller •The Motley Fool
••• ••
Axe Cap view
Rivian's $4.5 Billion DOE Loan: What It Means For Investors
Rivian’s government-backed loan offers attractive terms that ease short-term pressures but comes with indirect dilution and execution risks.
Rivian’s recent $4.5 billion Department of Energy loan for its Georgia factory is more than just cheap cash. The low interest rates and deferred repayment until around 2030 give Rivian valuable breathing room, particularly needed in the capital-intensive EV space. Unlike Lucid’s repeated equity raises that dilute shareholders, Rivian’s loan isn’t directly dilutive, but the linked $1.3 billion capital raise earlier this year did reduce existing holders’ stakes. For South African investors watching global tech and green innovation shifts, the takeaway is that well-structured debt can be a smarter way to fund growth than always issuing equity. However, early production in Georgia may underperform the Illinois plant, pressuring margins short term. For rand investors, the key will be how this impacts the USD/ZAR, given foreign exchange flows from capital raising and supply chain costs. A stronger dollar would pressure companies reliant on imported EV parts and tech. The risk? If global chip shortages or cost overruns hit harder, Rivian’s cash runway and equity buffer may shrink faster than expected. this is just our opinion and not financial advice
Watch Rivian and USD/ZAR closely. Consider trimming exposure to rand-hedged global tech plays if the dollar strengthens on ongoing capital flows. Avoid chasing Lucid’s equity patterns, but keep an eye on potential buy opportunities in well-funded EV names like Rivian once execution risks are clearer.
- USD/ZAR
- RIVN
- Global supply chain disruptions
- Rising USD strength impacting cost and earnings
5/10
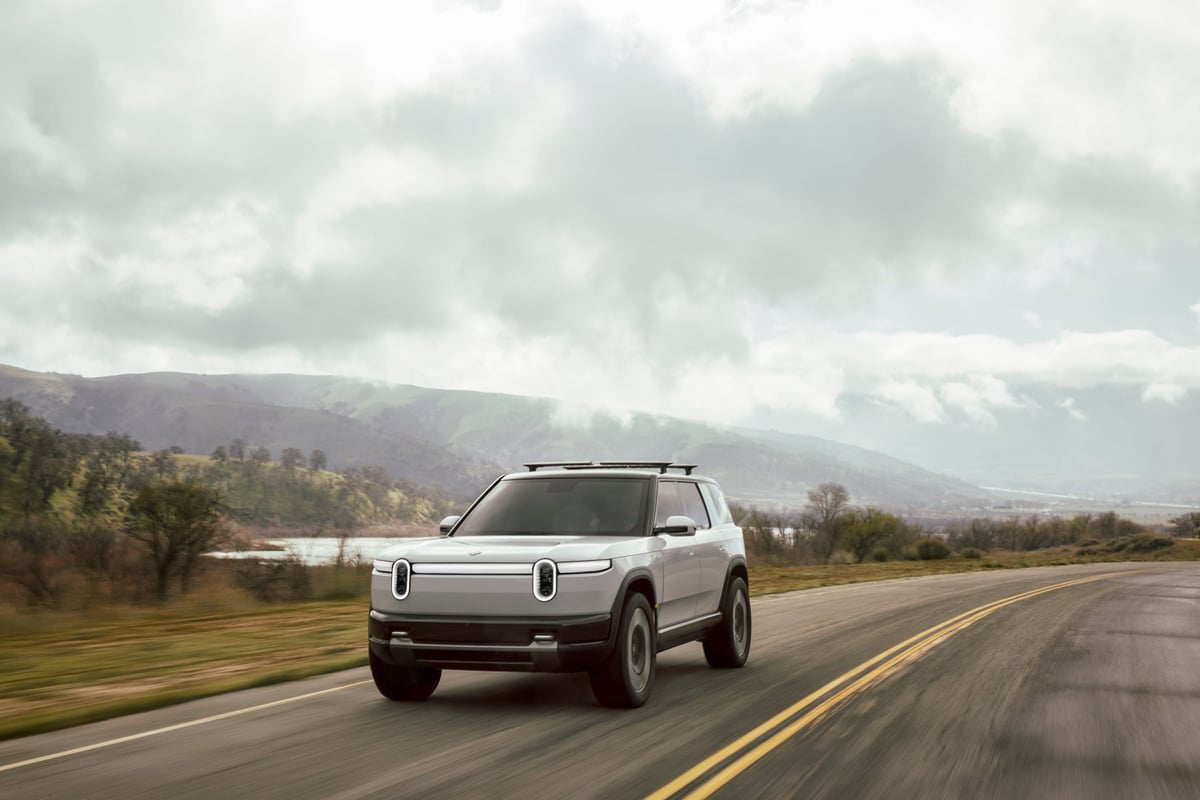
Rivian's $4.5 billion Department of Energy loan provides favorable financing for its Georgia factory construction with low interest rates and delayed repayment starting in 2030-2031. While the loan itself isn't directly dilutive, it indirectly required a $1.3 billion capital raise in July that diluted shareholders. The loan offers significant advantages including hundreds of millions in annual interest savings compared to other debt instruments and breathing room before repayment begins, though early Georgia plant production may initially be less profitable than the Illinois facility.
Our take is based on reporting first published by The Motley Fool.