
Micron Technology vs. Qualcomm: What Revenue Trends Tell Investors About These Tech Companies
 2026-10-04 05:20
•Robert Izquierdo •The Motley Fool
••••• ••••
Axe Cap view
Micron’s AI Surge vs Qualcomm’s Mobile Slump
Micron’s booming memory chip demand contrasts with Qualcomm’s declining smartphone business and strategic pivot.
Micron Technology’s revenue explosion—up 432% in two years—is a clear signal of how AI-driven demand is reshaping tech sectors. Their memory chips are crucial for data-hungry AI applications, giving them a rare growth edge. Qualcomm, on the other hand, is feeling the squeeze: smartphone sales are slowing due to higher component costs, squeezing margins and market share. They are now pivoting to AI data centers, a tough market with entrenched players. For South African investors, the takeaway isn’t to buy US tech blindly but to watch how these trends impact USD/ZAR and companies linked to global tech supply chains. Naspers and Prosus, with heavy tech exposure, could benefit if the US tech sector stabilizes, but their earnings remain vulnerable to these cyclical swings. If Qualcomm’s pivot succeeds, it might signal a recovery, but that’s uncertain. this is just our opinion and not financial advice
Watch: hold positions in Naspers and Prosus but trim if near-term volatility spikes; keep an eye on USD/ZAR strength from US tech sector shifts. Avoid Qualcomm for now until its AI pivot proves profitable.
- Naspers
- Prosus
- USD/ZAR
- Continued US smartphone weakness delays Qualcomm recovery
- Renewed US dollar strength pressures rand and SA tech counters
6/10
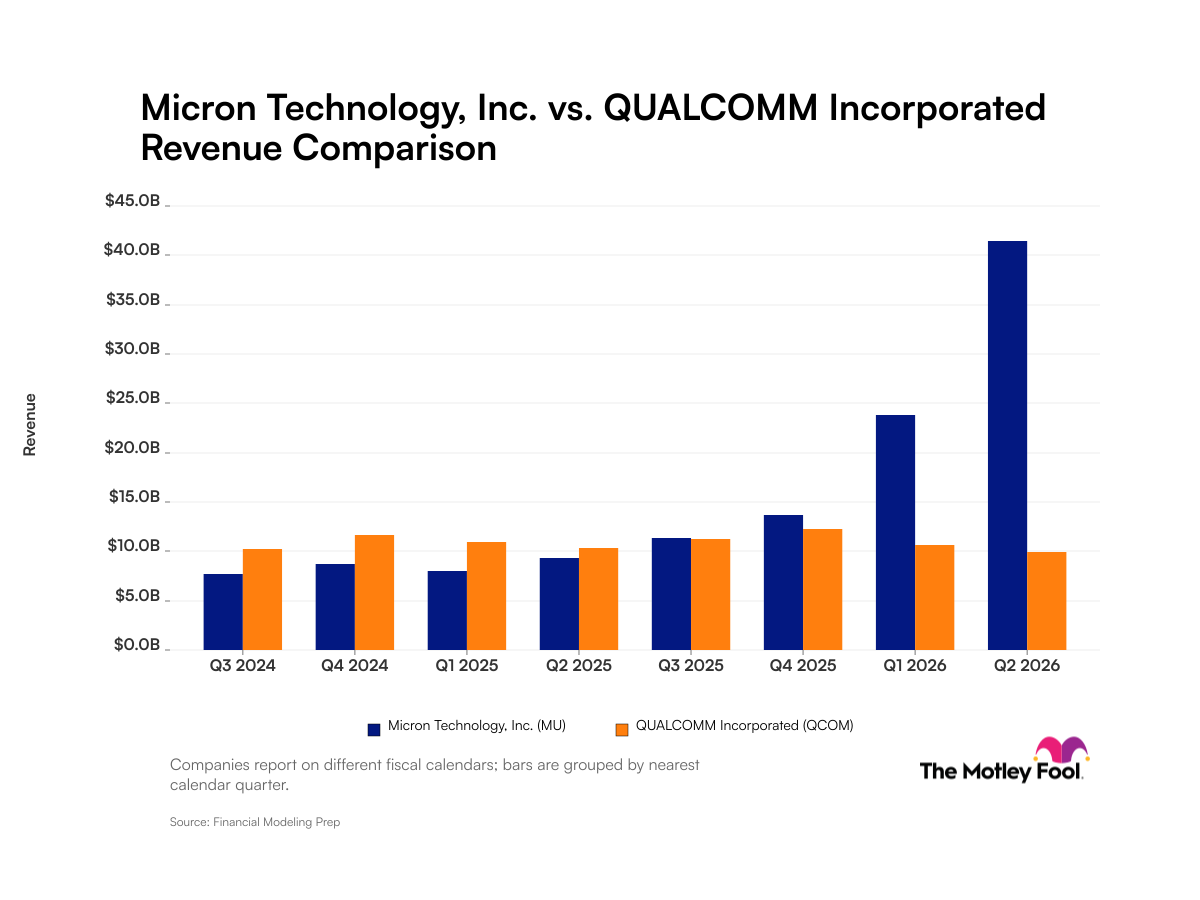
Micron Technology's revenue surged 432% over two years, reaching $41.5 billion in Q2 2026, driven by AI boom demand for memory chips. Meanwhile, Qualcomm's revenue declined in 2026 due to rising component prices compressing margins and reducing smartphone demand. Qualcomm is pivoting toward AI data centers to offset mobile business headwinds.
Our take is based on reporting first published by The Motley Fool.