
CrowdStrike vs. ServiceNow: Comparing Revenue Trends Between These Growing Software Giants
 2026-10-16 06:33
•Robert Izquierdo •The Motley Fool
••••• ••
Axe Cap view
CrowdStrike vs ServiceNow: Growth and Valuation Under the Microscope
Comparing two software giants reveals a clash between rapid growth and attractive valuation.
CrowdStrike’s streak of revenue growth and recent profitability are impressive, especially in the cybersecurity space known for resilience in tough times. But trading at nearly 200 times forward earnings borders on frothy. ServiceNow, though smaller in growth rate terms, dwarfs CrowdStrike in revenue and profits and trades at a much more reasonable 37 times earnings. For South African investors, the primary takeaway is how such high valuations in US tech might influence USD/ZAR. A sudden correction in expensive growth names could strengthen the rand as capital retreats from dollar assets. Local tech plays remain limited, so the rand’s direction is perhaps the best proxy for exposure here. If you buy into extended valuations, monitor closely for shifts in US money flows that could ripple through the rand, affecting sectors like Naspers and Prosus indirectly. The risk is that CrowdStrike’s lofty multiple collapses if growth slows or market sentiment shifts sharply. this is just our opinion and not financial advice
Wait on CrowdStrike’s valuation normalization before committing. ServiceNow offers a safer growth-at-reasonable-price play if you want US tech exposure through USD/ZAR. Protect exposure to rand fluctuations by watching US tech sentiment closely.
- USD/ZAR
- ServiceNow
- CrowdStrike’s growth slows, triggering sharp valuation drop
- USD strength erodes rand, impacting local listed tech stocks
6/10
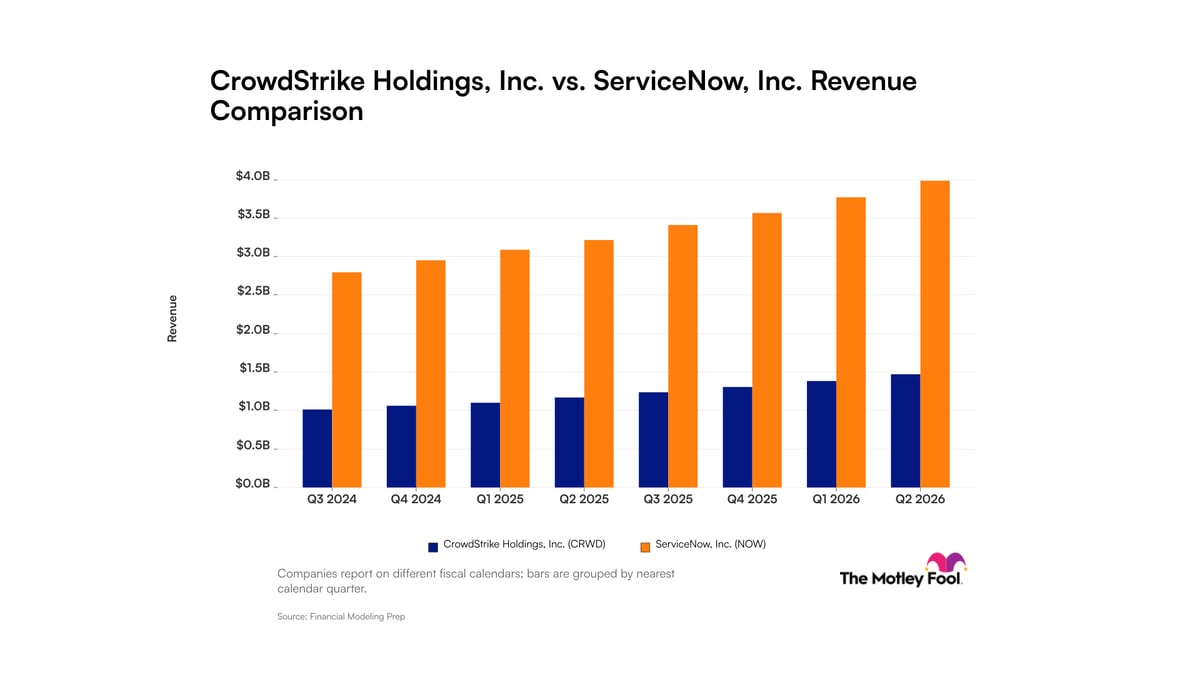
CrowdStrike and ServiceNow both demonstrate strong revenue growth with eight consecutive quarters of sequential increases. ServiceNow commands a 2.7x revenue lead ($4.0B vs $1.5B in Q2 2026), but CrowdStrike has achieved profitability in 2026. However, CrowdStrike trades at a significantly higher valuation (195x forward earnings) compared to ServiceNow (36.5x forward earnings), making ServiceNow appear more attractively valued despite both companies' solid operational performance.
Our take is based on reporting first published by The Motley Fool.