
Broadcom vs. SK Hynix: Here's What Revenue Trends Tell Investors About These Artificial Intelligence Companies
 2026-10-15 05:38
•Robert Izquierdo •The Motley Fool
•••••• •••
Axe Cap view
Broadcom vs. SK Hynix: Which AI Play Works for South African Investors?
SK Hynix’s AI-driven revenue surge overshadows Broadcom’s steady growth, but each poses distinct risks for local investors watching USD/ZAR closely.
SK Hynix’s rapid leap in revenue, driven by demand for high-bandwidth memory crucial to AI, is impressive—$52.6 billion in Q2 2026 easily beats Broadcom’s $29.6 billion. However, memory chips remain cyclical commodities. Prices can tank as supply adjusts to demand, hitting SK Hynix’s margins hard. Broadcom, on the other hand, grows steadily through AI data centre networking and software, less tied to commodity swings. For South African investors, the real lens is USD/ZAR. A stronger dollar inflates import costs but lifts earnings when translated back home — both SK Hynix and Broadcom report in USD. If the rand weakens amid global dollar strength, SK Hynix’s volatility risk may intensify locally. Broadcom’s predictability might be more attractive for portfolios that can’t stomach swings. This view could falter if memory chip prices stabilize longer than expected or if a sudden rand rally compresses USD returns. this is just our opinion and not financial advice
Watch USD/ZAR closely. If you expect rand weakness to persist, favour Broadcom’s steady American dollar earnings for smoother rand translation. Trim SK Hynix exposure unless you’re ready for bust-and-boom in memory pricing.
- AVGO
- SKHY
- USD/ZAR
- Volatility in memory chip prices affecting SK Hynix earnings
- Unexpected strengthening of the rand reducing dollar-based revenue benefits
6/10
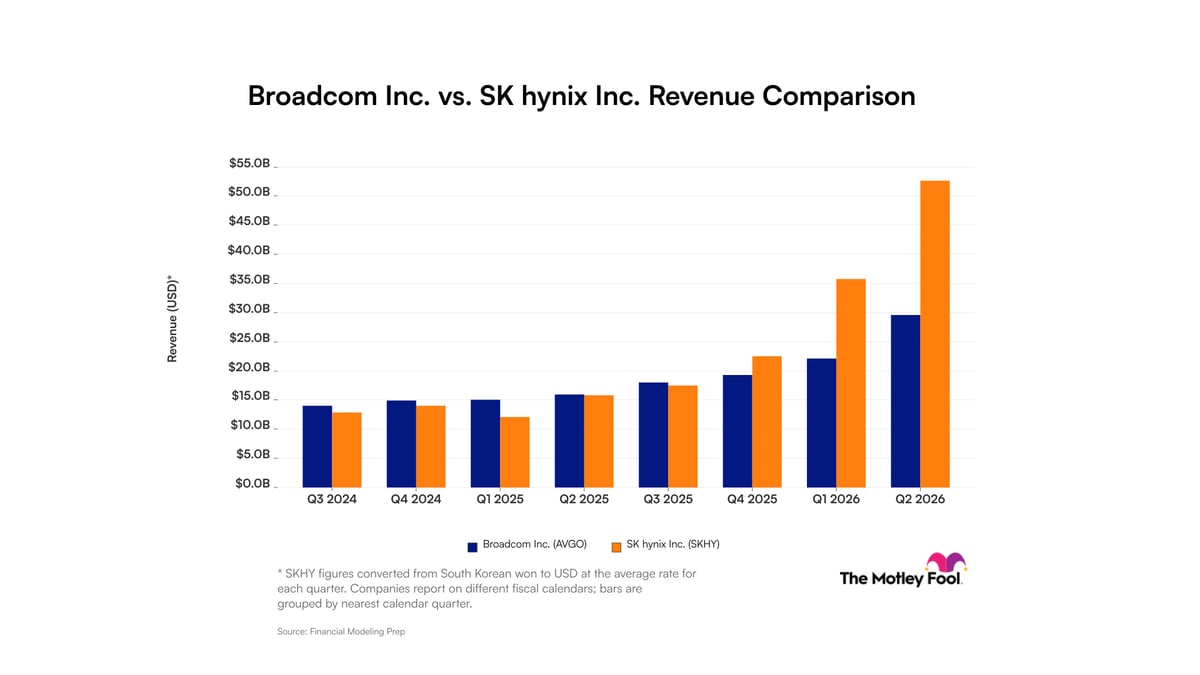
SK Hynix has surpassed Broadcom in quarterly revenue, driven by explosive AI-related demand for high-bandwidth memory (HBM) products, reaching $52.6 billion in Q2 2026 compared to Broadcom's $29.6 billion. While SK Hynix shows dramatic growth, it faces cyclical risks tied to commodity memory pricing. Broadcom maintains steady, predictable growth through its AI data center networking and infrastructure software, offering more stability despite slower expansion.
Our take is based on reporting first published by The Motley Fool.
More stories like this
- 1 of the Stock Market's Most Reliable Recession Warnings Just Disappeared. Here's What Usually Happens Next.
- Salesforce vs. ServiceNow: Here's What Revenue Trends Tell Investors About These Software Giants and Their Move to AI
- Google Just Started Paying SpaceX $920 Million a Month. Here's What That's Worth per Share.